The CPCA expects October passenger car retail sales of 1.6 million, down 28.9% year on year, and now forecasts full-year retail below the 2020 low.
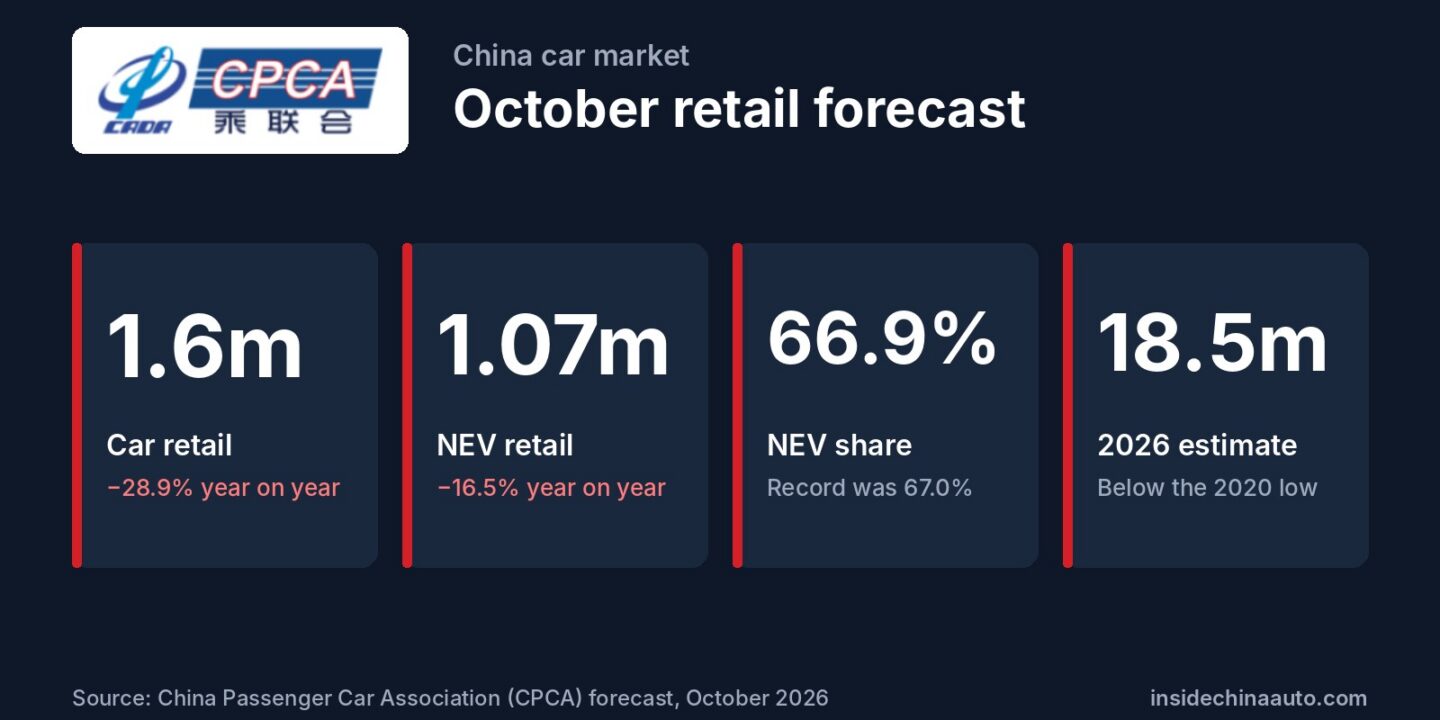
China’s car market is heading for another weak month, with the China Passenger Car Association (CPCA) forecasting October passenger car retail sales of about 1.6 million, down 28.9% year on year and 1.1% lower than September.
New energy vehicle retail sales are forecast at about 1.07 million, down 16.5% year on year and 1.3% lower than September. That would put NEV penetration at 66.9%, just below September’s record of 67.0%.
September and October are traditionally China’s peak selling months, but the CPCA says the boost from seasonal factors has weakened significantly this year.
Why sales are falling
The CPCA points to weak household income expectations, with buyers holding off on purchases, and to efforts to curb excessive price competition, which have limited discounting and squeezed dealer profits. Showroom traffic rose modestly over the National Day holiday but fell back afterwards.
High oil prices are weighing on petrol vehicle sales, while NEV demand has been relatively stable. The CPCA also says longer gaps between new models being unveiled, opening for pre-sale and reaching customers are lengthening buyers’ waiting times.
Most leading carmakers are cautious about the fourth quarter, according to the CPCA, with most having reached less than 60% of their annual targets after three quarters.
Daily retail sales averaged about 58,000 in the second week of October, helped by holiday orders, before falling to about 47,000 in the third week. The CPCA expects around 49,000 a day in the fourth week and about 79,000 in the final days of the month as carmakers push to hit month-end numbers.
Full-year retail below 2020
CPCA secretary general Cui Dongshu now expects 2026 retail sales of about 18.5 million, which would be lower than the 2020 trough. He describes the decline as steeper than previously expected and as an abnormal situation caused by several short-term factors coinciding.
Cui expects the domestic market to bottom out and return to growth in 2027, at between 0% and 5% with an average of about 2%, though he says the gap between stronger and weaker players will widen. Our monthly NEV sales and deliveries coverage will track how individual brands fare in October.